Briefings / Local Business
Small Businesses Are Renegotiating Debt Before the Pressure Breaks Them
A rise in restructuring requests shows where payment calendars no longer fit operating cash flow—and where early action can still preserve viable local firms.
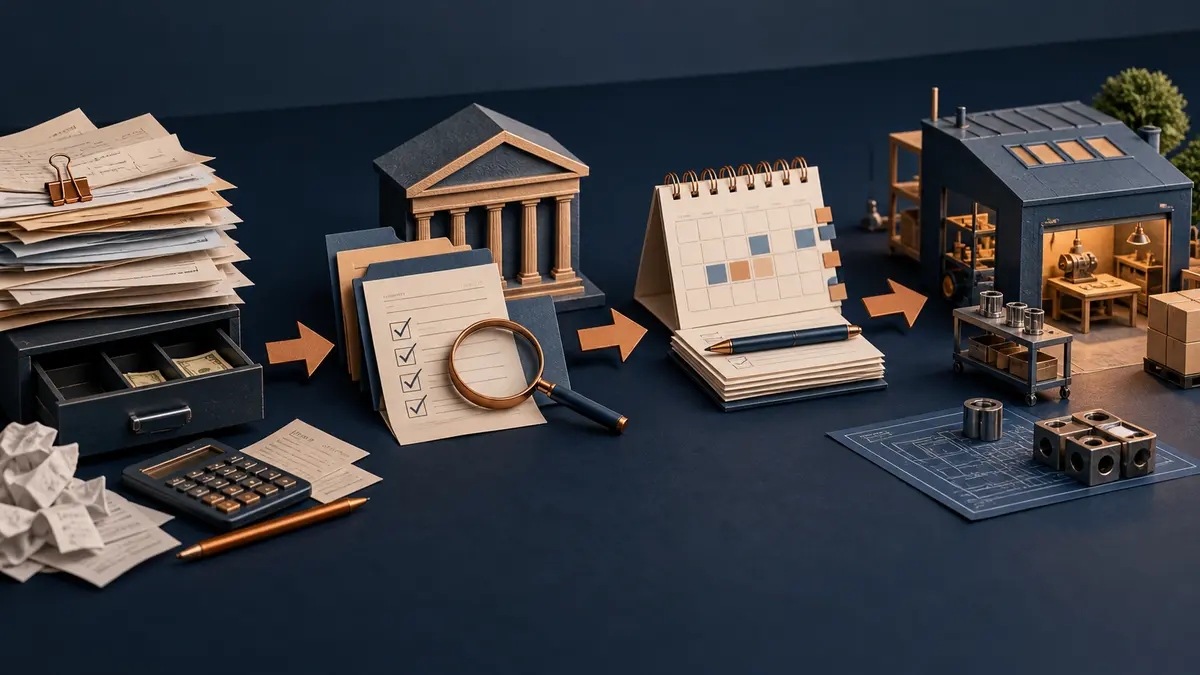
A rise in requests to rewrite small-business loan terms does not automatically mean a wave of defaults is coming. It does mean that the original schedules no longer fit the cash moving through thousands of firms. For lenders, local authorities and business owners, that makes restructuring data an early warning about where pressure is accumulating—and where a timely adjustment can preserve viable companies.
Debt problems rarely begin on the day a payment is missed. They begin when the rhythm of a company’s receipts stops matching the rhythm of its obligations. A customer pays two weeks later than usual. Inventory must be bought sooner. Payroll and rent remain fixed. Interest takes a larger share of each sale. The business may still have orders, useful equipment and a loyal market, yet the calendar that looked reasonable when the loan was signed becomes impossible to follow.
That mismatch became more visible in Russia during 2024. A November report by PRIME, drawing on a Bank of Russia information bulletin, said banks received 111,400 restructuring applications from small and medium-sized enterprises in the first nine months. The quarterly total rose from 35,100 in April–June to 40,400 in July–September. The increase was material, but its meaning depends on what happened to the firms after they asked for help.
Restructuring is a negotiation before it is a failure
A restructuring changes the contractual path of an existing debt. It may extend maturity, reduce near-term instalments, create a temporary grace period, move payment dates or consolidate several obligations. It does not erase the principal, and it does not make a weak business strong. Its purpose is narrower: to align debt service with a cash-flow pattern that has changed since the original underwriting decision.
This distinction matters because application totals can be read too dramatically. Some requests come from firms whose revenues have collapsed and whose prospects are poor. Others come from sound firms facing a temporary working-capital gap, a delayed public contract, a seasonal low point or an investment that will take longer to produce revenue. Treating every request as evidence of imminent default conceals the difference between solvency and timing.
The opposite mistake is equally dangerous. A bank may approve a modest extension and record the account as performing even though the borrower’s underlying margin has disappeared. A company can survive one revised schedule by postponing taxes, stretching suppliers or reducing maintenance. If the restructuring merely moves the pressure from the lender to employees, landlords and local vendors, it has not restored the business. It has redistributed distress.
Three tests for a viable adjustment
A useful restructuring must pass three tests. First, the company should have an operating core capable of producing positive cash after ordinary costs. Second, the revised schedule should be based on a conservative forecast rather than the sales target that failed under the original agreement. Third, the owners, lender and major creditors should share the burden in a transparent way. If only the maturity changes while the business model remains unexamined, the next request is already being prepared.
- Operating test: does the firm earn a contribution margin on its current products and customers before financing costs?
- Liquidity test: can it cover payroll, taxes, critical suppliers and the revised instalment under a realistic collection cycle?
- Balance-sheet test: is total debt supportable without relying on a permanent rise in prices or continuous refinancing?
- Governance test: will management provide timely accounts, expose related-party payments and accept agreed controls?
- Recovery test: does cooperation produce a better outcome for the lender than enforcement and asset sale?
The quarterly increase is more useful than the headline total
The PRIME figures show SME applications increasing by 5,300 between the second and third quarters, or roughly 15%. A quarter-to-quarter movement is informative because it identifies acceleration. The cumulative nine-month number, by contrast, combines different rate, demand and seasonal conditions. Neither figure should be interpreted without a denominator: the number and value of active SME loans, the share of repeat requests, approval rates and the amount of debt covered.
Application counts can also rise for benign administrative reasons. Banks may make restructuring channels easier to find, contact borrowers earlier or replace informal payment arrangements with documented programmes. Awareness can improve. A count dominated by small facilities carries a different systemic implication from a count driven by a few large medium-sized borrowers. The data becomes a warning signal only when it is connected to exposure and outcomes.
Still, requests contain information that arrears data reveals later. Owners usually know before a bank whether the next three months will be tight. They see customer conversations, empty shifts, delayed inputs and the true speed of collections. When more of them voluntarily seek new terms, the aggregate movement can identify a deteriorating environment before non-performing loan ratios respond.
Why local economies feel the pressure unevenly
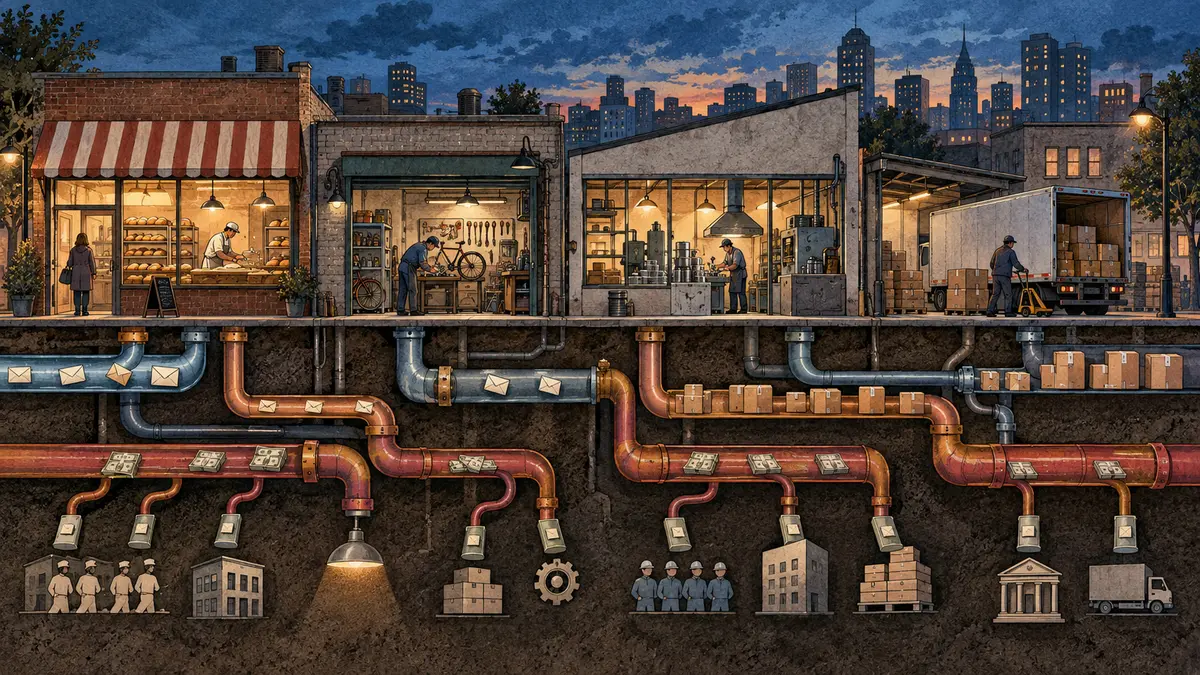
National monetary conditions do not arrive in every town in the same form. A diversified metropolitan service firm may replace a customer quickly or negotiate short billing cycles. A manufacturer in a smaller industrial city can depend on two buyers and hold months of specialized inventory. A tourism operator earns cash in one season but pays debt throughout the year. An agricultural supplier may be exposed simultaneously to weather, commodity prices and the payment discipline of farms.
Local market structure therefore determines how a credit shock propagates. Concentrated customers create correlated delays. Weak transport makes inventory buffers larger. Limited commercial property alternatives reduce a tenant’s bargaining power. Thin labour markets make it difficult to cut one activity and recruit for another. Municipal procurement can stabilize demand, but slow acceptance and payment can also create the working-capital gap that pushes a contractor toward restructuring.
The same variation affects recovery. A workshop with standardized equipment in a deep market offers a lender usable collateral. A specialized machine in a remote location may sell for far less than its book value. Closing the borrower can also damage the lender’s other local clients by removing a buyer, supplier or employer. In such places, a viable restructuring may protect more economic value than a narrow account-by-account model recognizes.
Authorities should not ask banks to preserve every company. That would weaken credit discipline and keep resources inside businesses that cannot recover. They should seek anonymized, aggregated evidence about sectors, municipalities and causes. A cluster of applications among otherwise healthy firms may point to a delayed procurement programme, utility disruption or transport bottleneck that public action can fix without interfering in individual credit decisions.
A calendar problem can become a margin problem
Working-capital stress often begins as timing but becomes structural when it lasts. A company borrows to finance receivables. Higher interest raises the cost of every delayed day. To protect cash, it buys smaller quantities and loses supplier discounts. It postpones maintenance, increasing downtime. It offers customers discounts for faster payment, reducing margin. Each defensive action makes the next period less profitable.
This feedback loop explains why early contact matters. Management has more choices before tax arrears, supplier disputes and overdue wages appear. It can cancel marginal product lines, sell idle assets, renegotiate leases, alter customer terms or stage investment. The bank can see reliable transactions while they still exist and design covenants around measurable actions. Once all parties are reacting to enforcement deadlines, the range of credible plans narrows sharply.
For a small company, the first restructuring document should be an operational cash bridge, not a persuasive essay. It should begin with bank balances and contractual receipts, then map essential outflows by week. Uncertain sales belong in a separate scenario. Owners should show which costs can be delayed without damaging revenue and which cannot. The requested payment schedule should follow from that model.
- Build a rolling thirteen-week cash forecast using actual collection dates rather than invoice dates.
- Separate temporary timing gaps from products, locations or customers that consistently destroy margin.
- Contact the lender before a missed payment and provide one reconciled set of accounts.
- Propose specific terms, milestones and reporting rather than asking for unspecified relief.
- Include owner measures such as dividend suspension, asset sales or additional equity where feasible.
- Stress-test the revised plan against slower receipts, weaker sales and one unexpected operating cost.
What lenders should learn from applications
An effective lender treats an application as both a credit case and a data point. At account level, it tests business viability, management candour, collateral and recovery alternatives. At portfolio level, it looks for common causes: industry margin compression, late payments from a large buyer, regional disruption, a particular loan vintage or underwriting assumptions that no longer hold.
Speed and segmentation are essential. A standardized short extension may work for seasonal firms with clean histories and a documented receivable. A manufacturer seeking a large maturity change needs a deeper operational review. Fraud indicators, repeated unexplained transfers or refusal to provide accounts require another path. Sending every applicant through the same slow committee wastes the time in which a viable firm can still act.
The revised contract should create information, not only delay. Monthly cash reporting, receivable ageing, inventory limits and restrictions on owner distributions can show whether the plan is working. Milestones should be few enough to manage and closely related to recovery. Excessive covenants can turn ordinary volatility into technical default and consume attention without protecting value.
Approval and rejection rates alone are poor measures of performance. A bank should follow cure rates, repeat restructuring, later default, cash recovered and the operating survival of borrowers. It should compare outcomes among similar cases. If a programme reports many approvals but repeatedly extends the same accounts, it may be postponing recognition. If it rejects most early requests and later suffers larger losses, its process may be acting too late.
Suppliers and employees are part of the credit picture
Bank debt is visible because it is contractual and reported. Trade credit is distributed across the local economy. When a firm preserves its bank instalment by paying suppliers later, the financing need moves to businesses with less access to credit. A strong buyer may impose ninety-day terms on a small vendor that must pay wages every two weeks. The vendor’s restructuring application is then partly a consequence of the buyer’s financing policy.
This is why payment discipline is an economic-development issue. Public bodies and large companies can reduce pressure by accepting work promptly, resolving invoice disputes quickly and publishing reliable payment calendars. Supplier-finance programmes can help when pricing and recourse are transparent. They become harmful when they normalize longer terms or force the smallest participant to finance the chain.
Employees experience restructuring through hours, wage timing and uncertainty. A credible plan should identify the workforce required for the viable core and communicate changes before rumours damage retention. Preserving every role for a few weeks and then closing abruptly is rarely kinder than an early, funded adjustment. Local employment services and training providers can respond better when aggregate sector signals arrive before layoffs.
A practical early-warning dashboard
No single number can distinguish a useful rise in early engagement from a deterioration in credit quality. A regional dashboard should combine applications with exposure, approvals, repeat cases, arrears, company closures and payment conditions. It should separate sectors and firm sizes while protecting borrower confidentiality. Trends should be compared with tax receipts, vacancies, procurement payment times and utility arrears.
Several ratios are particularly useful: applications per thousand active SME borrowers; debt under review as a share of SME exposure; the proportion of applicants not yet overdue; median days from request to decision; twelve-month cure rates; and supplier-payment days in affected sectors. A rise in early, non-overdue applications accompanied by strong cures may show a healthy adjustment mechanism. A rise in repeated applications, overdue taxes and supplier delays signals deeper impairment.
The dashboard should trigger questions rather than automatic rescue. Is pressure concentrated around one customer? Did an infrastructure interruption affect several firms? Are new loans underperforming because underwriting assumed old interest or demand conditions? Are viable companies requesting relief early, or are applications arriving only after cash is exhausted? Each answer points toward a different response.
The value lies in what happens next
The increase from 35,100 to 40,400 quarterly SME applications was an early signal, not a verdict on the whole small-business sector. It showed that more existing payment schedules were becoming difficult to maintain. Without approval, exposure and outcome data, it cannot by itself measure the eventual loss. But ignoring it until defaults appear would discard information supplied by borrowers closest to the operating economy.
Good restructuring preserves a viable enterprise while recognizing a changed reality. Bad restructuring protects appearances, shifts pain to weaker creditors or relies on a forecast no one believes. The difference is visible in cash evidence, shared sacrifice, realistic terms and disciplined follow-up.
For business owners, the lesson is to treat the lender as a stakeholder before the due date becomes a crisis. For banks, it is to connect individual decisions with portfolio and regional patterns. For local leaders, it is to remove common operational causes without directing private credit. Used this way, restructuring applications become more than a record of stress. They become a map showing where a local economy still has time to adapt.
Leave a comment